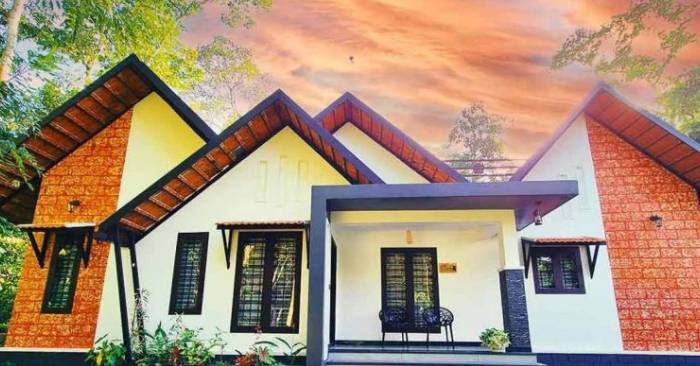
Deciding whether to rent or buy a house is one of the most significant financial and personal decisions an individual can make. While many think this choice is purely about money, it’s equally about your lifestyle preferences, long-term goals, and current circumstances. Buying a house is often seen as a step toward stability and independence. It not only builds personal assets but also provides the emotional security of owning a space where you can settle without external interference. Homeowners benefit from fixed loan repayments, customization freedom, and even tax incentives, making it a promising long-term investment—especially if property values in the area rise.
However, buying a home also comes with serious responsibilities and financial commitments. From hefty down payments to unexpected maintenance costs, ownership is not without its burdens. There’s also the risk that real estate prices may fall, potentially causing financial loss if you need to sell in a hurry. On the other hand, renting offers more flexibility and fewer responsibilities. It allows you to relocate easily and avoid the stress of property upkeep. It’s a smart option for those who aren’t ready to settle down or prefer to invest their money elsewhere.
That said, renting lacks the financial benefits of property ownership. You don’t gain equity, have limited control over the property, and may face yearly rent hikes. Plus, renters miss out on home-related tax deductions. Ultimately, the better option depends on your priorities—whether you value flexibility and lower short-term costs, or stability, equity growth, and the freedom of owning a home.